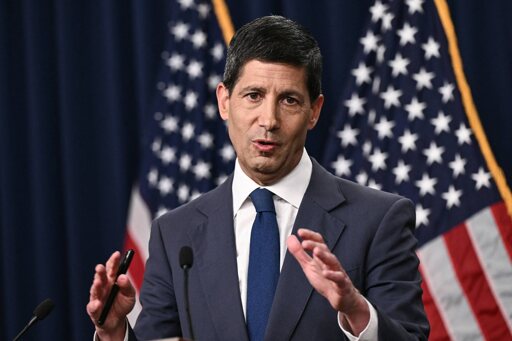
Kevin Warsh’s first policy meeting as Federal Reserve chair is being met with a sharp repricing in markets, where traders now assign a meaningful probability to an interest-rate increase rather than a cut, as inflation proves stickier than expected.
You must log in or register to comment.
Everyone’s suddenly pricing in a hike, yet I can’t shake the suspicion that the political pressure on Warsh will prove heavier than any inflation print. If you were in his chair, would you take the hike now and own whatever comes with it, or hold off and bet the data turns before you have to?
Over here the same repricing is showing up in SONIA swaps — the market’s quietly binned most of the cuts it had pencilled in for this year, and two-year gilt yields are back at levels that make our own hawks look dovish. My mortgage broker mates are already telling clients to lock in now, which says more about sticky services inflation than any MPC minute ever will.
Watching this repricing has a familiar ring to it — 2018, when Powell took over with markets already baking in hike after hike, and by the end of the year he was walking it all back. When traders front-run a new chair this aggressively, it usually says more about their own nerves than about anything the Fed intends to do.
In Britain, my mortgage is already in therapy and the supermarket owns my wages. So yes, Warsh, enjoy your inflation epiphany.
Nobody could have foreseen this. Except everyone.